By coincidence, you’re shopping in 2026 just as Newcastle’s price-to-income gap looks unusually favourable versus bigger UK hubs. You’ll find deposits and monthly payments that can work on graduate, NHS, or hybrid salaries, especially in well-connected neighbourhoods near the Metro. But affordability isn’t the whole story—new-build premiums, lease terms, flood pockets, and resale demand can flip the maths, and your next decision depends on what the numbers say about…
Key Takeaways
- Newcastle offers lower house prices than major UK cities, improving deposit and mortgage affordability for first-time buyers on local wages.
- Steadier post‑2021 price growth and longer sell times reduce volatility, making budgeting and mortgage stress testing more realistic.
- Strong demand from graduates, NHS staff, and remote workers supports entry‑level flats and terraces and helps maintain resale and rental liquidity.
- Well-connected neighborhoods near Metro, rail, and key employers (e.g., Heaton, Sandyford, Gosforth) balance commutes with long-term value.
- Lifestyle pull from walkable high streets, amenities, and culture (Quayside, St James’ Park, Theatre Royal) helps newcomers integrate and stay.
Is Newcastle Affordable for First-Time Buyers in 2026?
How affordable is Newcastle for a first-time buyer in 2026? You’ll likely find the numbers workable if you plan like an investor. Track Market trends: steadier annual price growth than the late‑2021 spike, with more listings and longer time‑to‑sell improving your negotiating power.
If you target well‑connected neighbourhoods near Metro and major employers, you can balance commute, safety, and resale.
Run your budget using current mortgage stress tests: assume rates stay higher‑for‑longer, and keep a 3–6 month buffer.
Buyer demographics matter too: strong demand from graduates, NHS staff, and remote workers supports entry‑level flats and compact terraces.
To feel part of the city fast, prioritise walkable high streets, local schools, and community groups.
Newcastle House Prices vs Other UK Cities
To sanity‑check Newcastle’s affordability, you’ll want clear price benchmarks (typical city‑wide averages and entry‑level terraces/semis) and how they stack up against major markets like London, Manchester, Birmingham, and Leeds.
You can then pressure‑test what you’d pay per month by comparing price‑to‑earnings and deposit requirements across those cities.
Finally, you’ll judge whether Newcastle’s value holds by lining up recent North East growth rates against other regions’ house‑price trends and volatility.
Newcastle Price Benchmarks
While headline UK house prices have stayed stubbornly high, Newcastle still benchmarks as a comparatively affordable entry point: typical values sit well below London, Cambridge, Bristol, Manchester, and Edinburgh, so your deposit and monthly repayments stretch further for the same budget.
Track sold‑price data by postcode and you’ll see clear micro‑benchmarks: Victorian terraces in Jesmond and Heaton price differently from semis in Gosforth, while city‑centre apartments move with rental yields and supply.
Use Historical housing trends to sanity‑check today’s asking prices versus five‑ and ten‑year baselines, not hype.
Then weight Neighborhood safety alongside school catchments and commute times to avoid false “bargains.”
When you benchmark like this, you’ll buy into a community that fits your lifestyle and feels securely yours.
Affordability Against Major Cities
Postcode‑level benchmarks tell you what “good value” looks like inside Newcastle; the next check is whether the city still wins on affordability when you stack it against other major UK markets. On current averages, Newcastle typically sits well below London, Manchester, Edinburgh, Bristol, and Birmingham, so your deposit stretches further and your monthly payments stay closer to local wages.
Compare like‑for‑like: a two‑bed flat or starter terrace in Newcastle often costs materially less than similar stock in those cities, even after accounting for commuting links and amenities. That gap supports Affordable housing without forcing you into fringe postcodes.
You also benefit from Market stability: fewer extreme price swings mean your mortgage stress‑test feels more realistic, and you can buy into a neighbourhood where friends can afford to stay, too.
Regional Growth Rate Comparisons
How fast does Newcastle actually climb when you benchmark its house‑price growth against other UK cities? Over the last 12–24 months, Newcastle has generally tracked mid‑table: it hasn’t matched Manchester or Birmingham’s peak surges, but it’s often outpaced slower‑moving southern markets where affordability caps demand.
You’ll typically see steadier quarterly gains rather than spikes, which matters if you’re planning a first purchase, not a flip.
Look at the drivers: Regional economic momentum from public‑sector stability, expanding digital and green industries, plus demographic shifts as graduates and remote workers stay or return.
Compared with Leeds and Sheffield, Newcastle can look slightly tighter on supply, which supports prices. If you want to feel part of a rising city, you’re not late—you’re timing it.
What Salary You Need to Buy in Newcastle
Because lenders base affordability on income, deposit size, and current mortgage rates, the “salary you need” to buy in Newcastle boils down to a simple equation: your budget equals your deposit plus what a bank will typically lend you (often around 4–4.5× your annual income, subject to stress tests).
If you’re targeting a £180,000 starter home and you’ve saved £18,000, you’ll need roughly £162,000 of borrowing—often implying a £36,000–£40,500 salary.
Stretching to £220,000 with the same deposit typically pushes income toward £45,000–£50,000.
Track Market trends street by street: prices vary sharply between Jesmond, Heaton, and Gateshead.
Compare mortgage options (fixed vs tracker, term length) to keep repayments aligned with your day-to-day life and future plans.
First-Time Buyer Costs in Newcastle: Deposit to Bills
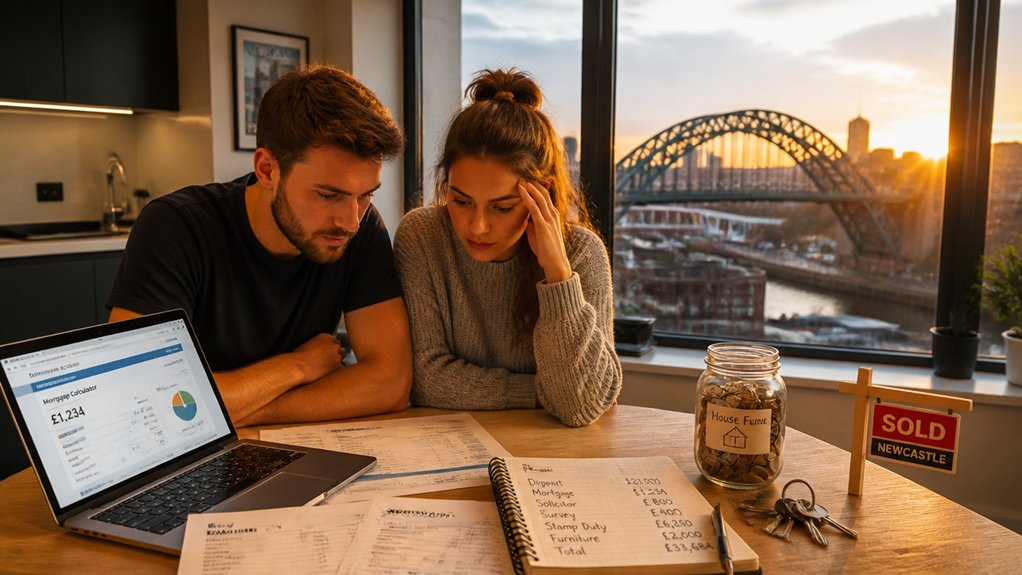
Once you’ve sized your borrowing power and target price, the next step is mapping the cash you’ll need from offer to moving day—because in Newcastle, the deposit is only the headline number.
If you’re aiming for a 10% deposit, budget another 2%–5% for stamp duty (where applicable), conveyancing, searches, surveys, and lender fees.
Add moving costs, initial furnishings, and a contingency fund so you don’t start stretched.
Your monthly run-rate matters too: mortgage payments sit alongside utilities, insurance, commuting, and childcare.
If you’re switching from Affordable rent, expect higher fixed outgoings and fewer “pause months.”
Factor Property taxes and service charges (if leasehold) into your affordability test, so you can settle in confidently.
Best Newcastle Neighbourhoods for First-Time Buyers
While Newcastle’s price points still vary street by street, you’ll get the best first‑time buyer value by focusing on neighbourhoods that balance entry‑level stock, strong transport links to the city centre, and proven demand drivers like universities, major employers, and regeneration spend.
In Heaton and Sandyford, you’ll find high rental demand and steady resale interest, with terraces and Tyneside flats that suit smaller deposits.
Gosforth costs more, but strong local schools and low void risk support long‑term value.
Jesmond skews premium, yet smaller flats can still work if you’re buying for future liquidity.
For sharper pricing, look at Walker, Byker, and parts of Benwell where refurb stock and regeneration can lift equity, but check streets carefully.
Prioritise Community amenities so you’ll feel rooted fast.
Commuting in Newcastle: Metro, Rail, Roads
When you buy in Newcastle, your commute’s value comes down to Metro coverage and frequency—especially how quickly you can reach the city centre and key employment hubs without relying on a car.
You’ll also want to price in regional rail links for access to Sunderland, Durham, and beyond, since faster connections can widen your job catchment and support resale demand.
On the roads, you can’t ignore A1/A19 access and peak‑hour congestion, because those minutes lost (or saved) directly affect day‑to‑day costs and the premium buyers will pay in different neighbourhoods.
Metro Coverage And Frequency
Because commute time directly affects what you can afford and where you’ll realistically live, Newcastle’s Metro coverage and service frequency deserve a hard look before you bid. The network links the airport, city centre, and key north/south corridors, so you can price homes by station access, not guesswork.
In peak windows, many core sections run every 6–12 minutes, which lowers reliance on cars and stabilises your weekly costs.
If you want consistent Public transport, check how often your stop gets trains after 7pm and on Sundays, not just weekday peaks.
Higher Housing density clusters around well-served stations, so you’ll compete harder there—but you’ll also feel plugged into neighbourhood life, with easier meetups and routines.
Regional Rail Links
How far can you realistically stretch your search radius beyond the Metro? Regional rail makes it viable. Northern Rail and LNER connect Newcastle Central to Durham, Sunderland, and the Tees Valley, while the Tyne Valley line reaches Hexham and Carlisle.
If you target stations with half-hourly or hourly peaks, you’ll keep commutes predictable and protect resale demand.
Newcastle Central’s role in the region’s historical development still underpins strong footfall and employer access, which buyers price in.
You’ll also plug into cultural attractions fast: Quayside events, St James’ Park, and the Theatre Royal sit within a short walk or one stop.
Check season-ticket costs versus rent savings, and prioritise walkable stations for a smoother daily routine.
Road Access And Congestion
Where do Newcastle’s roads actually work in your favour—and where will congestion quietly eat into your budget and patience? If you drive in from Gosforth, Jesmond, or Heaton, you’ll often get reliable access to the city core and the A1 for weekend escapes.
But peak-hour pinch points around the Central Motorway, Tyne Bridge approaches, and Coast Road can slow traffic flow and nudge fuel and parking costs up.
You’ll feel the difference when you time viewings: test the route at 8am and 5pm, not midday. Check planned road maintenance, because closures can reroute you into longer queues.
If you’re buying to settle in, pick streets with multiple exits and bus-lane alternatives—you’ll move like a local, not a visitor.
New-Builds vs Terraces in Newcastle: What Suits You?
While Newcastle’s first‑time buyer demand stays strong, the choice between a new‑build and a terrace will shape your monthly costs, maintenance workload, and resale prospects.
New‑builds often price at a premium, but you’ll typically get stronger energy efficiency, lower running costs, and fewer surprise repairs in years one to five. You also gain smoother move‑in timelines and modern layouts that fit hybrid work.
Terraces can deliver sharper £/sq ft value in established streets, plus walkable amenities that help you feel part of the city’s rhythm. You’re buying Historic architecture, access to Cultural festivals, and neighbourhood identity.
Budget for ongoing upkeep, then balance it against character, centrality, and long‑term demand from buyers who want roots in a community.
Newcastle Buying Risks: Floods, Leases, Resale
Although Newcastle remains a comparatively affordable entry point, you’ll protect your budget and future resale by stress‑testing three risks early: flood exposure (especially in low‑lying river corridors and pockets with historic surface‑water issues), leasehold terms that can quietly inflate monthly outgoings, and resale friction tied to EPC ratings, cladding status, or non‑standard construction—so run a flood search, scrutinise the lease, and sanity‑check local demand before you commit.
Treat Flood risks like a price factor: insurers may load premiums, and lenders can tighten terms on flagged postcodes.
With Leasehold issues, model ground rent, service charges, reserve funds, and any review clauses; ask for the last three years’ accounts.
For resale, check EPC trajectory, EWS1/cladding paperwork, and construction type against what local buyers and agents actually shift fast.
Do this, and you’ll buy into the right streets confidently.
Conclusion
In 2026, Newcastle can still feel like a door you can actually open: prices sit well below many UK hotspots, so your deposit and repayments aren’t fighting gravity. If your salary matches local lending norms, you’ll find workable routes—terraces for value, new-builds for predictability. Pick neighbourhoods with strong transport and amenities, and you’ll keep commuting costs lean. Stay sharp on flood risk, lease terms, and resale demand.
About the Author